Landlord liability insurance pays first for covered rental claims. An umbrella adds liability coverage above it – not a replacement. My starting point: check each rental’s coverage before buying more. Even a $1 million umbrella won’t automatically cover an excluded claim.
For landlords in Raleigh, Durham, Chapel Hill, and the Triangle, I’d check three things:
- The property and owner: Confirm every address, rental use, LLC, or trust qualifies under both policies.
- The claim terms: Check exclusions, legal defense costs, deductibles, reporting deadlines, and required underlying limits – often $300,000 or $500,000, depending on the umbrella.
- The gaps: Building repairs and lost rent need separate coverage. Disclose pools, pets, vacancy, renovations, and short-term rentals, and confirm the property manager’s insurance duties.
Quick Comparison
| What I’d check | Landlord liability | Umbrella |
|---|---|---|
| Role | First layer for covered liability claims | Added coverage above required underlying limits |
| Limits | Policy-specific; $100,000 to $1 million or more may be available | Commonly starts at $1 million |
| Legal defense | Check whether costs reduce the limit | Check when defense duties begin and end |
| Eligibility | Must match the rental, use, and insured owner | Must accept the rental and ownership setup |
| Exclusions | Restrict which claims qualify | Has its own exclusions; does not automatically fill primary-policy gaps |
| Building damage and lost rent | Not covered by liability alone | Typically not covered |
My rule: <u>get coverage requirements and rental eligibility confirmed in writing</u>. Then compare higher primary limits with umbrella coverage – and review both at renewal or whenever ownership or rental use changes. The policy terms, not just the dollar amount, determine what protection you have.
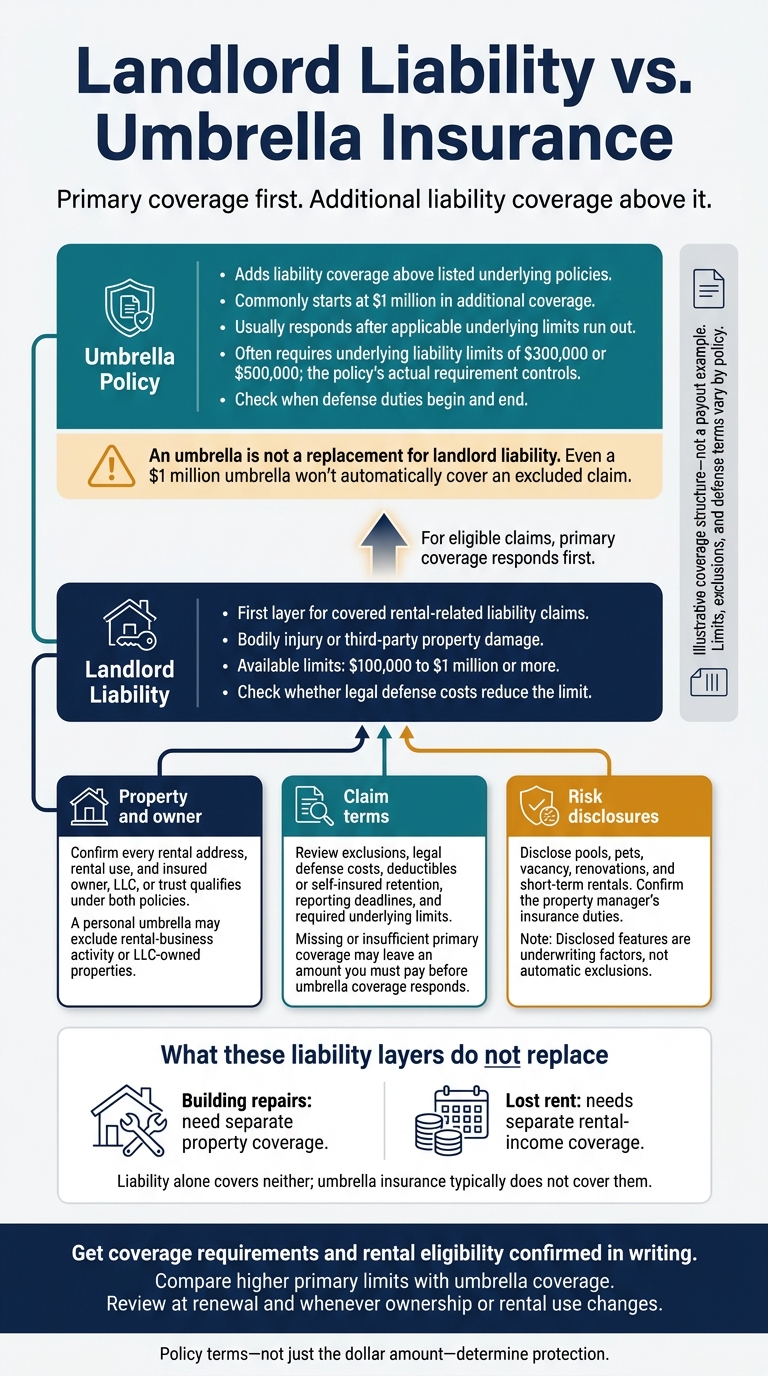
Landlord Liability vs. Umbrella Insurance: How Coverage Works
Umbrella Insurance for Landlords: Does It Really Cover Your Rentals?
sbb-itb-aa27f6d
Landlord Liability vs. Umbrella Insurance: Key Differences
Landlord liability coverage handles covered liability claims first. Coverage for building damage and lost rent is separate. An umbrella policy adds liability coverage above the policies it lists, subject to its terms.
| Issue | Landlord liability coverage | Umbrella policy |
|---|---|---|
| Purpose | Provides the first layer of protection against covered rental-related liability claims. | Adds liability protection above listed underlying policies. |
| Covered risks | Covers bodily injury or third-party property damage claims, including defense costs and covered settlements or judgments. | Covers eligible liability claims above underlying limits, plus any additional claims specified in the policy. |
| Building damage and lost rent | Liability alone covers neither. Separate dwelling and rental-income provisions may cover these losses after covered property damage. | Typically does not pay to repair your building or replace rental income. |
| Claim sequence | Investigates and defends a covered liability claim first. | Usually responds after the applicable underlying limits run out. |
| Limits | Available limits range from $100,000 to $1 million or more. | Commonly starts at $1 million in additional coverage. |
| Underlying requirements | Must meet the umbrella policy’s requirements for coverage and minimum liability limits. | Often requires underlying liability limits of $300,000 or $500,000. The policy’s actual requirement controls. |
| Addresses and ownership | Must reflect the rental location, its use, and the insured owner or entity. | Rental addresses and LLC or trust ownership must qualify. A personal umbrella may exclude rental-business activity or LLC-owned properties. |
| Exclusions | May exclude or limit intentional acts, mold, pollution, and other risks. Understanding legal best practices for NC landlords can help mitigate risks not covered by insurance. | Has its own exclusions. A claim excluded by the primary policy does not automatically qualify for umbrella coverage. |
| Best use | Provides premises-liability protection within a properly structured landlord policy. | Adds coverage for large covered liability claims – not a replacement for the landlord policy. |
Policy Terms That Affect Rental Claims
Once you know the policy type, check how defense costs, deductibles, and limits affect what it pays toward a claim.
Landlord Liability: Claims, Limits, and Gaps
For bodily injury or third-party property damage claims, check whether defense costs reduce the liability limit or are paid separately. Also confirm who chooses counsel and when the insurer’s duty to defend ends.
Check any deductible or self-insured retention – the amount you must pay before the policy responds. A per-occurrence limit caps payment for one covered event. An aggregate limit caps payment for covered claims during the policy period.
| Provision | Advantage | Limitation to check |
|---|---|---|
| Liability payments | May pay covered settlements and judgments | Exclusions and available limits restrict payment |
| Legal defense | May provide counsel for covered allegations | Defense expenses may reduce funds available for a settlement |
| Medical payments | May pay limited medical expenses without proof of negligence | Separate eligibility rules and smaller limits apply; this does not replace liability coverage |
Building damage and lost rent need separate property or rental-income coverage. Medical payments cover only limited injury expenses.
Umbrella Insurance: Required Coverage and Rental Eligibility
Ask the umbrella carrier to confirm in writing the required underlying limits and which rental activities, addresses, unit counts, and insured entities qualify. If primary insurance is missing or its limits are too low, you may have to pay the difference before umbrella coverage responds.
Check terms that mirror the underlying policy, along with exclusions, defense obligations, and any self-insured retention. An umbrella does not fix an excluded primary claim or replace property and loss-of-rent coverage.
For Triangle rentals, these terms must match the property’s actual address, ownership, and rental use.
North Carolina Rentals: Addresses, Owners, and Exclusions
Compare the declarations pages and endorsements with the deed, lease, management agreement, and umbrella schedule. If those documents don’t match the rental’s actual setup, umbrella coverage may not respond.
Ask whether the property manager needs additional-insured status. Being listed as an additional interest does not provide liability coverage. Report changes in ownership, occupancy, or rental use promptly – don’t wait for renewal.
Before you bind or change coverage, disclose pools, trampolines, pets, vacancy, renovations, and short-term rentals. These details affect claim eligibility and help the insurer match coverage to how the property is owned, used, and managed.
Request written answers about fencing, locking gates, animal restrictions, vacancy deadlines, maintenance standards, and required endorsements. Review exclusions for mold, pollution, intentional acts, and contractually assumed liability. Inspection photos and repair records help document property conditions, but they cannot override an exclusion.
Choosing Coverage for Triangle Rentals
Once you understand how each policy works, match coverage to the property’s risks. Start with the landlord policy: check that each rental has adequate liability limits before pricing umbrella coverage. Get property-specific quotes to compare higher liability limits with umbrella coverage. Factor in the risks, ownership structure, and carrier requirements.
The right setup depends on whether you own a single rental, a portfolio, or a property with higher-risk features.
Single Properties, Portfolios, and Higher-Risk Features
For a single Triangle rental, check that the policy includes premises liability. A basic dwelling-fire policy may need an endorsement. Then confirm whether the rental qualifies for umbrella coverage.
For a portfolio in Chapel Hill, keep one schedule listing every address, owner, policy, limit, deductible, and renewal date. Check it against deeds and leases before requesting quotes. An LLC-owned rental may need commercial umbrella or excess coverage.
For condos and townhomes, review the association’s master policy, declaration, and bylaws. Confirm who is responsible for interiors, balconies, plumbing, and deductibles. Association insurance does not replace the owner’s landlord policy.
Include pools, older systems, pets, contractor visits, and heavy visitor traffic in quote requests. These are underwriting factors – not automatic exclusions.
Clear reporting and documentation duties help liability and umbrella claims move forward under the policies’ terms.
Property Management and Insurance Duties
Review the management agreement for required coverage, insured parties, certificate deadlines, indemnity terms, and deductibles. Also check who handles incident reporting, recordkeeping, and claims communication. Follow the policy’s reporting rules; notifying the manager is not enough.
Conclusion: Check Primary Coverage Before Adding an Umbrella
For landlords in our service areas, landlord liability provides the first layer of coverage for covered rental claims. An umbrella policy adds liability limits when it meets the carrier’s requirements. It does not replace building or loss-of-rent coverage.
Use this checklist to confirm that your primary policy and umbrella work together before a claim occurs.
Landlord Insurance Review Checklist
- Gather the full policies. Collect declarations, endorsements, exclusions, schedules, and full policy forms for every rental policy. Confirm per-occurrence limits, aggregate limits, deductibles, and required underlying limits in writing.
- Match properties and eligibility. List every address, unit, and ownership entity. Confirm that both policies match the rental use, and review pools, pets, short-term rentals, vacancy, contractors, and business activities. An umbrella does not override a primary policy exclusion.
- Check how claims use your limits. Confirm whether defense costs reduce the available limit, whether limits apply per property or across the portfolio, and when umbrella coverage begins. Review notice deadlines, cooperation duties, and required records.
- Close gaps before making changes. Get written confirmation of any needed coverage changes before binding coverage. Repeat the review at renewal and after acquisitions, ownership transfers, occupancy changes, or new risk features.
FAQs
How much umbrella coverage do I need for my rentals?
The amount of umbrella coverage you need depends on your total asset exposure. If you own multiple properties in the Triangle, an umbrella policy can offer cost-effective liability protection beyond your standard landlord policies.
Standard landlord policies typically include $300,000 to $1,000,000 in liability coverage per policy. Umbrella coverage adds protection against large claims, often costing $150–$500 per year for an additional $1,000,000 in coverage.
Should I raise my liability limits or buy an umbrella?
The right amount of coverage depends on your total risk exposure. Standard landlord insurance typically includes $300,000–$1,000,000 in liability coverage. If you own multiple Triangle properties, an umbrella policy can add $1,000,000 in coverage beyond your standard policy limits for $150–$500 per year.
Either way, require tenants to carry renters insurance with at least $100,000 in liability coverage to help reduce your personal risk exposure.
Should I notify both insurers after a tenant injury?
Yes – notify both your landlord insurance and umbrella insurance providers after a tenant injury. Umbrella coverage sits above your primary landlord policy, so both insurers generally need notice to coordinate coverage and handle claims that may exceed your primary policy’s limits.
If you use a property manager, they can help coordinate with both insurers and make sure claim documents are handled correctly and promptly.